FAQ
The questions that come up most, with the answers Scott actually gives. If yours isn't here, it's a text away.
Working with Scott
How do I get in touch with Scott Synovic?
Text or call 303-668-3350 — texting is fastest. You can also email scott.synovic@fairwaymc.com or start an application through his official Fairway Home Mortgage profile. Scott is based at Fairway's Monument, CO branch and serves buyers and homeowners in Monument, Colorado Springs, Castle Rock, the Denver south metro and across Colorado.
What does it cost to ask Scott a question?
Nothing. Questions, payment estimates, refinance break-even math, reverse mortgage comparisons and pre-approval conversations are free. Lender costs only appear if and when you close a loan, and they are disclosed on your Loan Estimate.
Who is Scott Synovic?
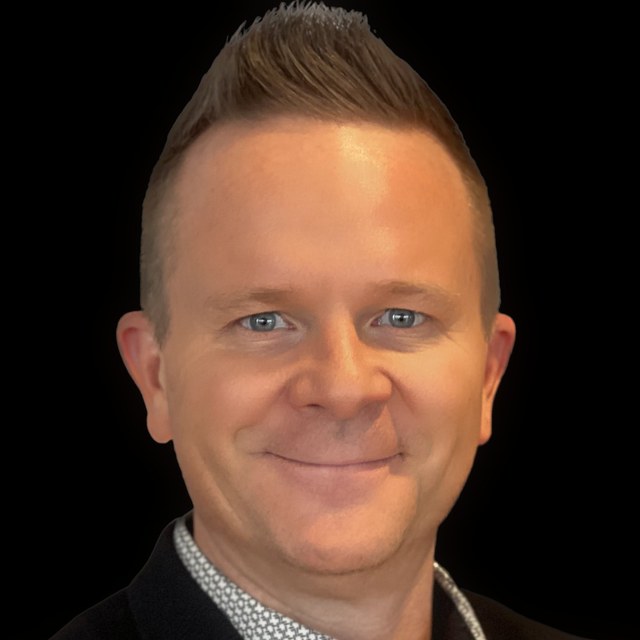
Scott Synovic is a Loan Officer with Fairway Home Mortgage (NMLS #253799) in Monument, Colorado. He has worked in mortgage lending since 2003, is a multi-year Five Star Mortgage Professional award winner, and originates both traditional mortgages and reverse mortgages (through Fairway Reverse). He is licensed in Colorado.
Does Scott do reverse mortgages?
Yes. Scott originates Home Equity Conversion Mortgages (HECMs) and HECM for Purchase loans for homeowners 62 and older through Fairway Reverse, Fairway's dedicated reverse mortgage division — alongside conventional, FHA, VA, USDA and jumbo loans. The reverse side of this site is at /reverse/.
Do I need a real estate agent to work with Scott?
No — but Scott works best as part of a team with your agent, and he can introduce you to agents he trusts if you do not have one. You are always free to choose any licensed agent.
Is Scott available on evenings and weekends?
Scott aims to be reachable seven days a week, because showings and offer deadlines do not keep office hours. Text is the fastest way to reach him.
Money questions
How much do I need for a down payment?
As little as 3% on conventional loans for qualified first-time buyers, 3.5% on FHA, and $0 on VA or USDA loans for eligible buyers. Down payment assistance from the Colorado Housing and Finance Authority (CHFA) and local programs such as metroDPA may cover some or all of it for eligible households.
What credit score do I need to buy a house?
Conventional programs generally start around 620. FHA guidelines allow lower scores with 3.5% down. If your score is not where you want it, Scott can map out what moves it and when buying makes sense.
What will my monthly payment be?
Use the calculator on this site for an instant estimate including principal, interest, taxes, insurance and mortgage insurance. Then text Scott the address and price for numbers specific to that home and your scenario — including the metro-district taxes and hail-zone insurance that make Colorado payments different.
What are closing costs?
Fees to finalize the loan and transfer the home — typically roughly 2–4% of the purchase price. They can sometimes be covered partly by seller credits or lender credits, within program limits.
Can my family help with the down payment?
Yes. Gift funds from family are allowed on conventional, FHA, VA and USDA loans with a gift letter and a documented transfer.
Can I buy a house on one income?
Yes. Single buyers and one-income households qualify every day. Lenders look at your debt-to-income ratio, not the number of names on the application, and programs like FHA, USDA and CHFA down payment assistance are built for buyers who qualify on income but are short on savings.
Military & VA questions
Can I use a VA loan to buy near Fort Carson, Peterson or the Air Force Academy?
Yes. Eligible veterans, active-duty service members and surviving spouses can use a VA loan anywhere in Colorado, including Colorado Springs, Fountain, Monument, Falcon and Peyton. VA loans require $0 down and have no monthly mortgage insurance. Scott pulls your Certificate of Eligibility electronically as part of pre-approval.
Can I use my VA loan more than once?
In most cases, yes. VA entitlement can be restored once a prior VA loan is paid off, and some veterans have enough remaining entitlement to buy again before then — common for PCS moves. Scott checks your entitlement before you shop.
Does BAH count as income for a mortgage?
Yes. Basic Allowance for Housing and other non-taxable military allowances generally count as qualifying income on VA and other loan programs, and some programs allow them to be "grossed up" because they are not taxed.
Refinancing questions
Should I refinance my mortgage?
Refinance when the total savings outlast the cost. The quick test: divide the closing costs by the monthly savings — that is how many months until the refinance pays for itself. If you will stay in the home well past that point, it is worth a real look. Scott runs the break-even math for free and will tell you to keep your current loan if that is the better move.
How much does it cost to refinance?
Typical refinance closing costs run roughly 2–3% of the loan amount, and they can often be rolled into the new loan. The exact figure is shown on your Loan Estimate so you can compare the cost to the monthly savings before you decide.
Can I refinance to get rid of FHA mortgage insurance?
Often, yes. With roughly 20% equity, refinancing from an FHA loan into a conventional loan can remove mortgage insurance entirely — sometimes saving hundreds a month even when the rate barely changes.
What is a cash-out refinance?
A cash-out refinance replaces your current mortgage with a larger one and gives you the difference in cash — commonly used for renovations, consolidating higher-interest debt, or other large goals. It is a new first mortgage with its own rate and term, so the break-even math matters just as much as it does for a rate-and-term refinance.
I am over 62 — is a reverse mortgage better than a cash-out refinance?
It depends on what you want the money to do and how long you plan to stay. A cash-out refinance adds a new monthly payment; a reverse mortgage (HECM) has no required monthly payment but the balance grows over time. Scott originates both and compares them side by side, including a HELOC and the option of doing nothing, so the decision is yours with real numbers.
Timing questions
How long does pre-approval take?
Typically a day or two once Scott has your complete documents — often the same day. Incomplete paperwork is the most common delay, which is why the pre-approval checklist exists.
Does getting pre-approved hurt my credit?
A mortgage pre-approval is one hard inquiry — typically a few points, temporarily. Multiple mortgage inquiries in a short shopping window count as one.
How long does it take to close on a house?
Commonly 30–45 days from accepted offer to closing, depending on the contract, appraisal and underwriting. Scott sets a realistic date with you and your agent on offer day.
Should I wait for rates to come down?
Nobody can predict rates. The better question is whether the payment fits comfortably today. If rates fall later, refinancing is an option; the purchase price you lock in today never changes.
Colorado questions
Is there down payment assistance for first-time home buyers in Colorado?
Yes. The Colorado Housing and Finance Authority (CHFA) pairs its first mortgages with a down payment assistance grant or a deferred, 0%-interest second mortgage for eligible buyers, and local programs such as metroDPA (Denver metro) and the El Paso County Turnkey Plus program add more options. Income and purchase-price limits apply and change; Scott checks eligibility as part of pre-approval.
Why are property taxes lower in Colorado but payments still surprise people?
Colorado's effective property tax rates are among the lower ones in the country, but many newer neighborhoods in Monument, Castle Rock, Falcon and the Denver south metro sit inside metropolitan districts that add their own mill levy to pay for infrastructure. Two similar homes can carry very different tax bills. Scott pulls the actual tax figure for any address before you write an offer.
Why is homeowners insurance expensive along the Front Range?
Hail. Colorado's Front Range is one of the most hail-prone regions in the country, and wildfire exposure in foothill and forested areas (Black Forest, parts of Monument and Palmer Lake) adds to it. Insurance is part of the monthly payment, so Scott recommends getting a quote on any serious house before you write.
Does Scott lend outside the Colorado Springs area?
Yes. Scott is licensed statewide in Colorado and works with buyers and homeowners from Pueblo to Fort Collins, with most clients along the Front Range between Colorado Springs and Denver. The process is the same anywhere in the state: text, phone, video, secure upload, and a closing at a title company near you.
Ready when you are
No dumb questions, no pressure, no forms to fill out. Text Scott what you are wondering about and get a straight answer — usually the same day, nights and weekends included.
Applications happen on Fairway's secure site — never here.